
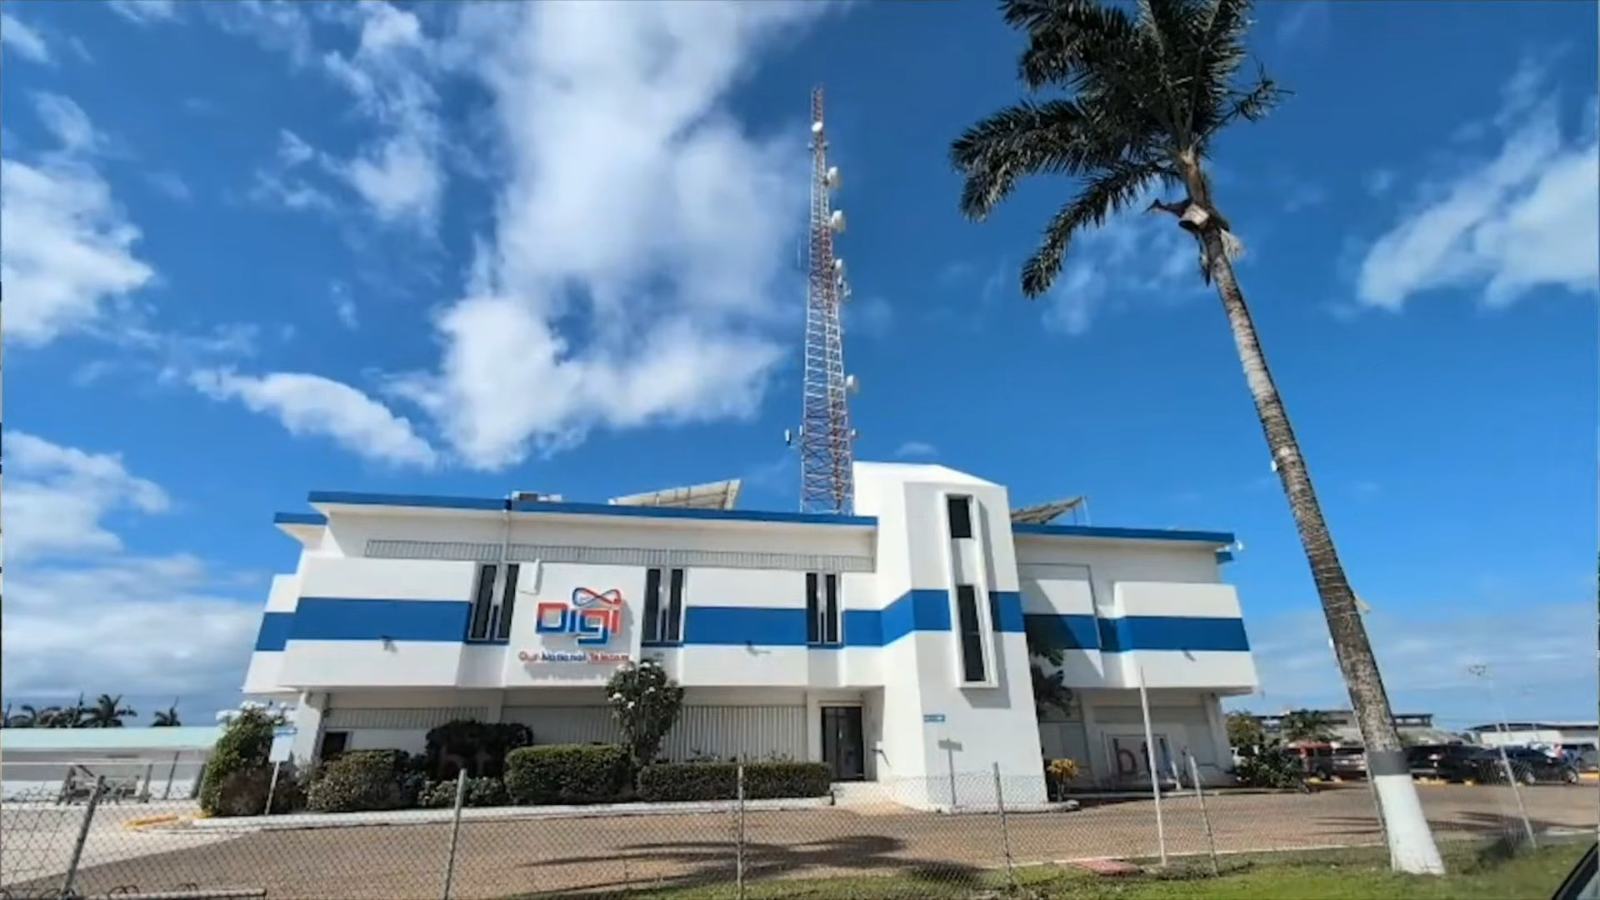
BTL's proposed $80 million acquisition of Speednet Communications Limited is being framed as a strategic upgrade for national infrastructure. However, we've been studying the numbers and the analysis of the financial projections, legal boundaries, and corporate governance reveals a deal pitched by the seller on questionable accounting assumptions, significant public risk, and clear anti-competition concerns.
Jules Vasquez reports:
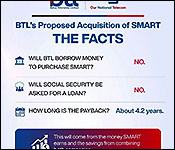
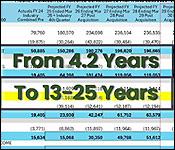
BTL and the seller claim the $80 million price tag is justified by an estimated 4.2-year payback period. However, the underlying numbers reveal key discrepancies.
First, there's the omission of financial ratios: BTL's public communications emphasize a "4.2-year payback" without providing the standard metrics used for public investments - such as Net Present Value, Internal Rate of Return, or a formal Discounted Payback schedule.
The 4.2-year recovery claim appears to rely on simple payback math: dividing the $80M purchase price by an assumed $19M annual net profit. But simple payback can be too simple; it ignores the time value of money, future operating capital expenditures, and debt service costs.
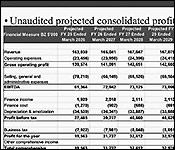
And then there's the financial modeling by Moore Belize - which is one of the only documents that board members received. It projects Speednet will generate $69.1M in revenue with a massive 66.5% profit margin - far higher than BTL's own 44% margin.
But, if Speednet's annual revenue is closer to $28M-$32M, the realistic payback timeline expands from 4.2 years to 13-25 years.
Proponents highlight that core profits will nearly double from $65M to $119M, but company slides show total sales stop growing as soon as the deal closes.
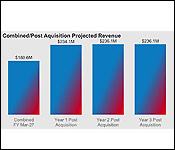
Combined revenue would increase to $234.1M in financial year 2027 as Speednet is subsumed, but that revenue grows by less than 1% annually through financial year 2029.
So, because revenue growth goes flat, the projected jump in profit seems to depend almost entirely on aggressive cost reduction.
Lord Ashcroft's press release confirms planned reductions in power costs, software licenses, maintenance, and duplicated corporate functions - including sales, marketing, HR, finance, IT, and purchasing.
Neither BTL nor the Government has disclosed the exact scope of planned redundancies or downsizing to Speednet staff.
Beyond the financial metrics, the transaction eliminates Belize's only second major mobile and broadband operator, creating a national telecom monopoly.
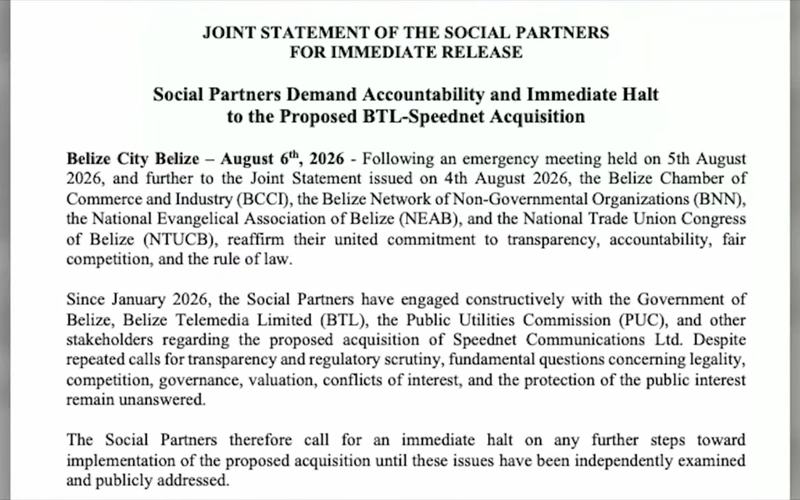
As the social partners have pointed out, Section 42(4) of the Telecommunications Act explicitly prohibits any licensee from entering agreements that have the effect of "significantly lessening competition in any market for the supply of telecommunication services." They have called for an "immediate halt" to the acquisition.
BTL is a publicly owned private company and key questions have not been answered:
Will BTL release Speednet's full audited financial statements for the past 5 years to verify actual revenue and profit margins?
Why were standard valuation metrics omitted from public disclosures and board consideration?
How will the PUC enforce Section 42(4) of the Telecommunications Act to prevent a complete market monopoly?
We'll continue to look more closely at the numbers next week.